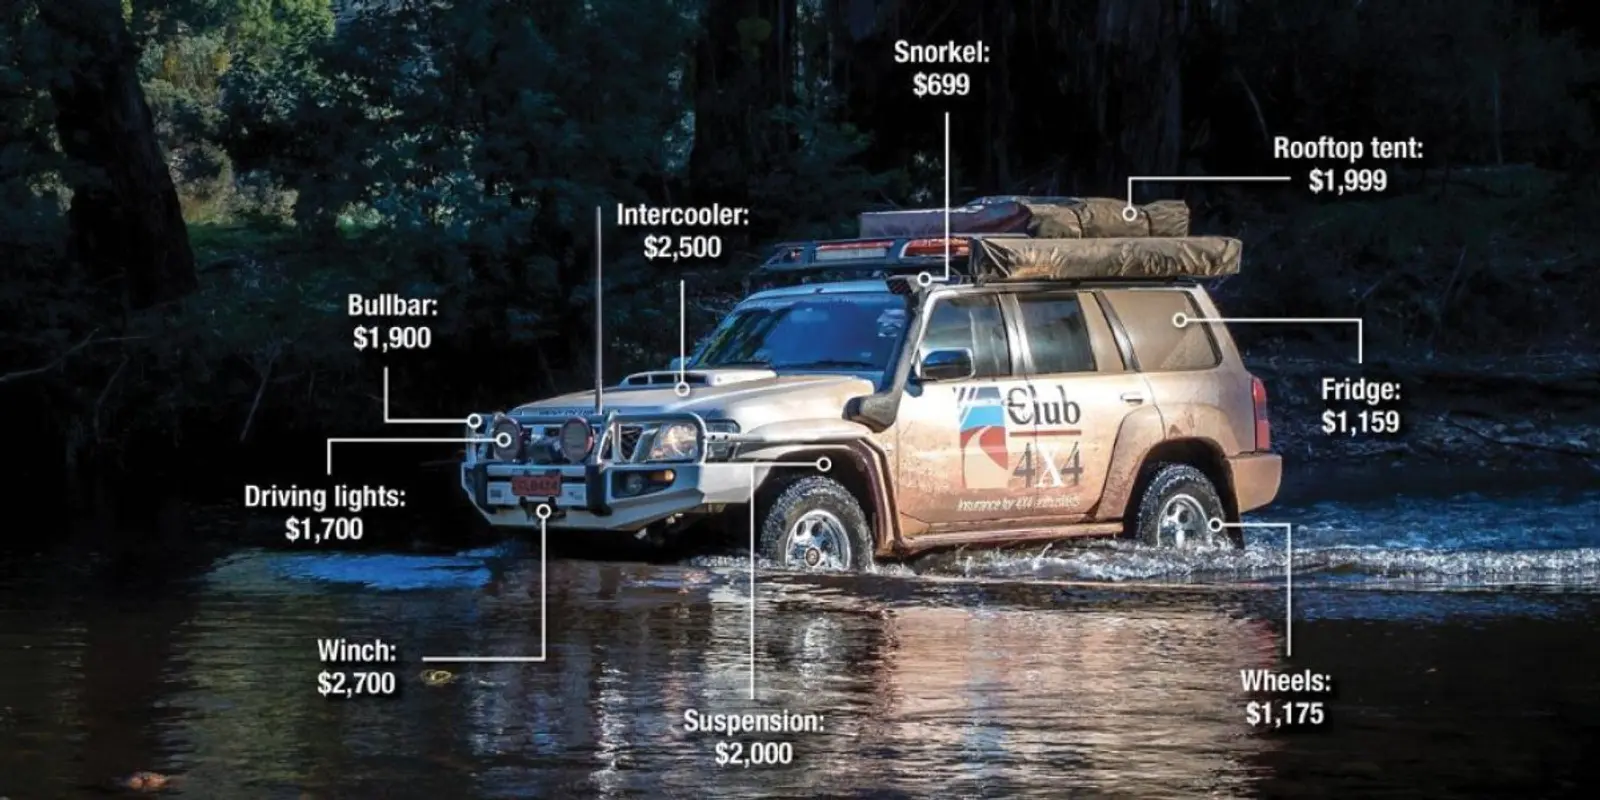
The Two Parts of Your 4WD's Value
When you're insuring a modified 4WD, there are really two key values to think about: the vehicle itself, and everything you've added to it.
The vehicle can generally be insured for either Market Value or Agreed Value. Market Value is the reasonable market-related value or our assessment of what the general market would pay for your vehicle, without modifications, at the date of its loss or damage. based on what the vehicle’s worth at the time of a covered total loss or theft, while Agreed Value, on the other hand, is an amount set with the insurer for the policy period.
But Mmodifications and accessories are a separate consideration.
At Club 4X4, your modifications and accessories are insured for their own Agreed Value, separate from the value of the vehicle itself. That means your bull bar, winch, suspension, canopy, electrical setup and other declared gear aren't simply expected to disappear into the value of the base vehicle.
The adventure starts where the bitumen ends
See how Club 4X4 can help
Market Value vs Agreed Value for the Vehicle

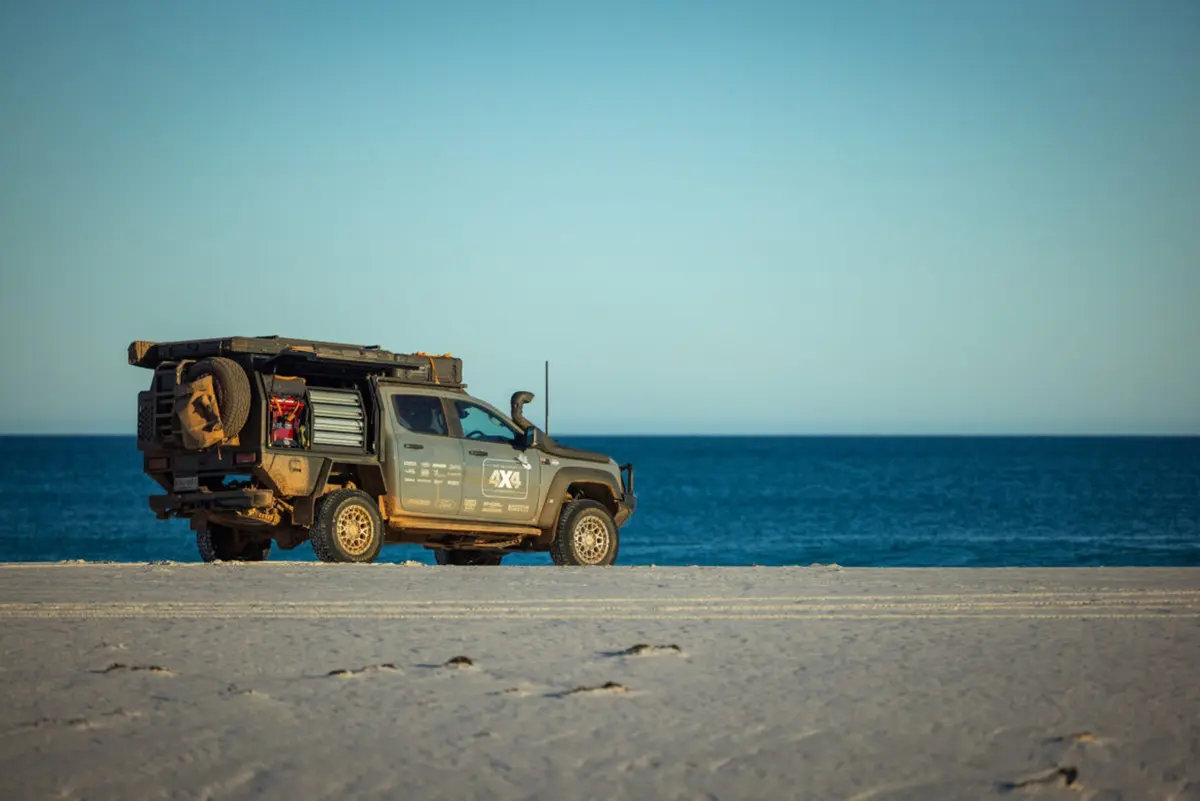
a grey, modified 4X4 Ford Ranger ute
For the vehicle itself, Market Value can make sense if you're comfortable with its value being determined at claim time. It will naturally move as the vehicle gets older and the used-car market changes.
Agreed Value gives you more certainty. You and the insurer agree on the vehicle's insured value when the policy is taken out or renewed, rather than determining its value after a total loss.
For a touring 4WD, though, the value of the vehicle is only part of the equation. A five-year-old dual-cab ute might have tens of thousands of dollars invested in modifications and accessories, and that value needs consideration.
Why Modifications Need Their Own Value
Picture that five-year-old dual-cab. Then add a bull bar, winch, suspension upgrade, canopy, drawers, fridge slide, dual-battery system, roof rack, driving lights, long-range tank and upgraded wheels.
A modified touring 4WD can have $30,000 or more in eligible modifications and accessories fitted in addition to the vehicle itself.
That's why Club 4X4 separates the two. You could, for example, choose Market Value for the vehicle whilste having $30,000 of declared modifications and accessories insured at their own Agreed Value.
In other words, you don't necessarily need to put the entire 4WD build under one agreed figure. The base vehicle has its insured value, and your declared modifications and accessories have theirs.
What to Include in Your Modifications and Accessories Value
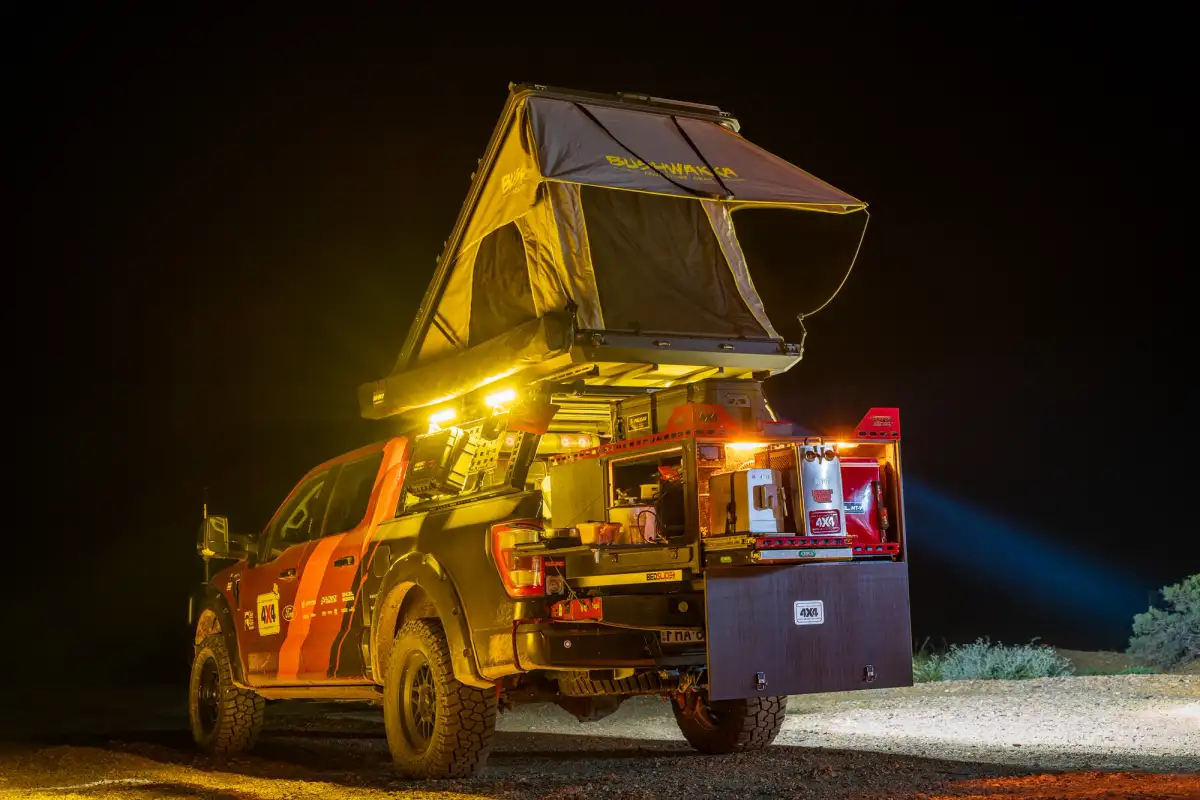
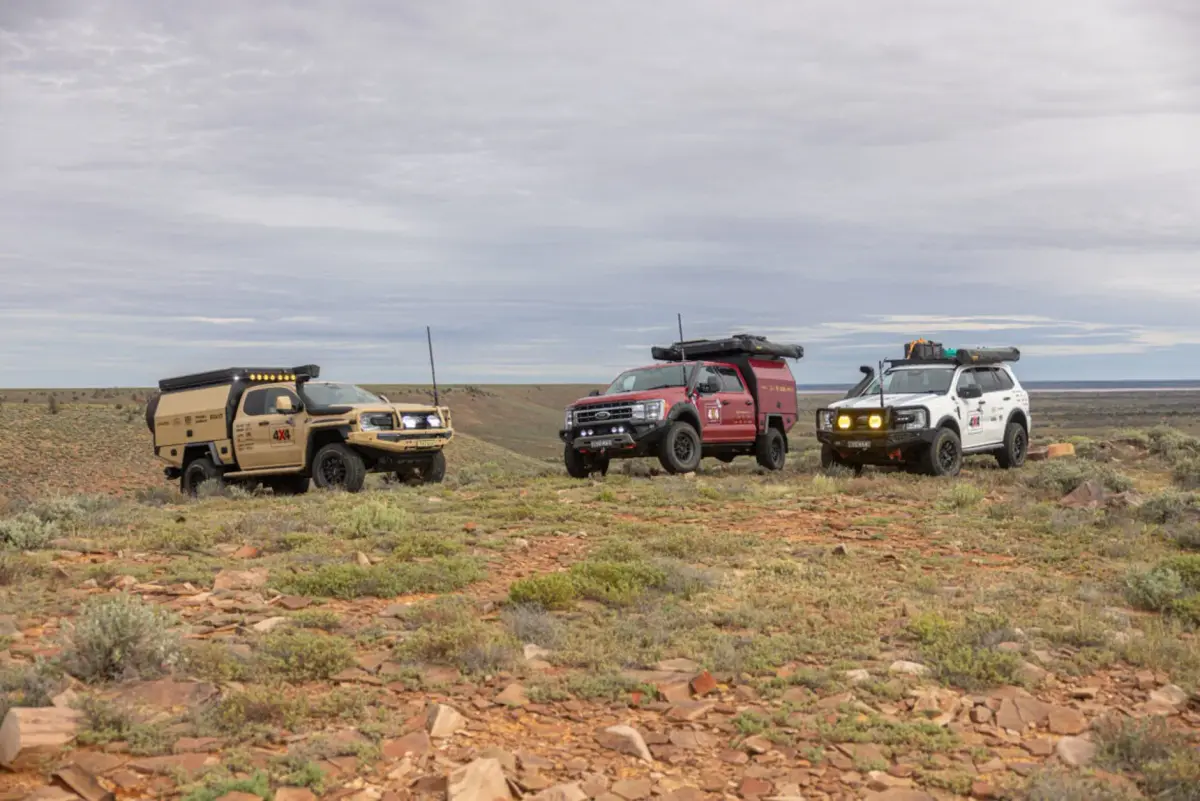
A red, modified 4X4 Ford F-150 ute with its canopy and rooftop tent open
Club 4X4’s mModifications and accessories cover is designed for eligible items that have been added to or modified on the vehicle, rather than everything associated with a 4WD or every dollar spent on a build.
Depending on the policy terms, eligible modifications and accessories can include:
- Protection and recovery: bull bar, side steps, rock sliders, underbody protection, recovery points and permanently fitted winch.
- Suspension and touring upgrades: suspension upgrades, GVM upgrades, canopy, drawers, roof rack, awning and long-range fuel or water tanks.
- 12V and electrical: permanently installed batteries, DC-DC chargers, solar systems, inverters and lighting.
- Communications: permanently fitted UHF radios, aerials and navigation equipment.
- Other modifications: snorkels, diff breathers and eligible engine or driveline modifications.
There are some important exclusions. Loose or removable gear isn't automatically a modification or accessory just because you carry it in the 4WD. Items such as camping gear and removable equipment, including a fridge that can be taken off its slide, may instead fall under personal effects cover where eligible and subject to the applicable limits.
Consumable or perishable components such as tyres also shouldn't simply be added to your modifications value.
And importantly, this isn't a way of insuring the money you've spent maintaining or restoring the vehicle. Restoration work, repairs and replacing worn components don't automatically add to the modifications and accessories Agreed Value. The focus is on eligible modifications and accessories you've added to the vehicle, rather than the total amount you've invested in getting it to its current condition.
Keep the Figure Current
Your 4WD probably won't stay exactly the same for long.
If you add a new canopy, lithium setup, suspension upgrade or another major modification during the policy period, let your insurer know. Otherwise, your existing modifications and accessories Agreed Value may no longer accurately reflect the build sitting in the driveway.
Keep invoices and photos of eligible modifications as you add them, and if you have a Club 4X4 policy, you can update the agreed value whenever the build changes, not just at renewal. That makes it much easier to keep the separate Agreed Value for your modifications and accessories aligned with what's actually fitted to the vehicle.
Review the vehicle's insured value separately at renewal. If you've selected an Agreed Value for the vehicle, check that you're still comfortable with it. If you've selected Market Value, remember that its value isn't locked to the amount the vehicle was worth when you first bought the policy.
Our article on the questions to ask before renewing covers some of the other things worth checking each year.
What About the Caravan or Camper?

A man kneeling by the rear of a caravan
Your tow rig isn't the only thing that can change after purchase. Solar, lithium batteries, awnings, diesel heaters and other upgrades can add significant value to a caravan or camper too. Check how these additions are treated under your caravan insurance or camper trailer insurance, including whether they need to be declared separately and whether any limits apply.
Where Club 4X4 Sits
Club 4X4 was built with modified and touring 4WDs in mind. With our 4WD insurance, you can insure the vehicle itself for either Market Value or Agreed Value, while your declared modifications and accessories are insured separately for their own Agreed Value.
That means the value of your touring setup doesn't have to be treated as though it's simply part of a standard vehicle. Whether you've added a bull bar and winch or built a fully equipped touring rig, the important part is making sure you've declared what's fitted and selected an appropriate value for it.
Cover extends anywhere in Australia you're legally allowed to drive, on-road or off-road, subject to the policy terms, conditions and exclusions. Check the PDS for the full details.
The adventure starts where the bitumen ends
See how Club 4X4 can help